Reach us on WhatsApp straight away using the button at the bottom left
This article came out of a real question: can two people buy a home together in the UK? The short answer is yes. The long answer is that who is named on the title, and with what share, changes everything from stamp duty to inheritance.
How many names can be on the title?
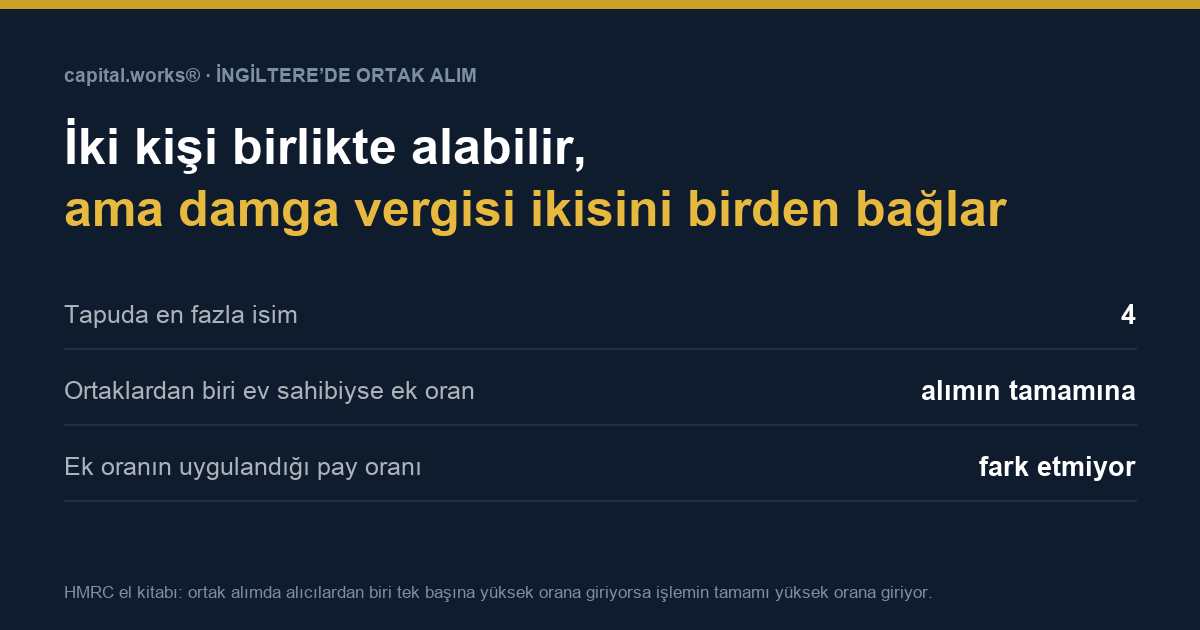
HM Land Registry records at most four names against a property. Where a larger group is buying, those four hold the property on trust for the rest, and the actual shares are set out in a separate deed.
There are two forms of co-ownership, and choosing wrong is expensive to undo
Joint tenants. Shares are not divided: everyone owns the whole property together. When one owner dies, their interest passes automatically to the other regardless of any will. This is the usual choice for married couples.
Tenants in common. Here the shares are defined: they can be 50 and 50, or 70 and 30. When one owner dies their share does not pass automatically to the other but goes to their heirs under their will. This is the structure that suits partners, siblings and friends who put in different amounts.
This choice is a legal act and belongs to a solicitor. We manage the process and the flow of documents; your solicitor sets up the structure on the title.
The real trap is stamp duty
This is the point most often missed in a joint purchase, so let me put it plainly. If any one of the joint buyers owns residential property anywhere in the world, the additional dwelling stamp duty applies not to that person’s share but to the entire purchase.
HMRC’s own manual puts it this way: in a joint purchase, if any one of the buyers would fall within the higher rates when considered on their own, the whole transaction falls within the higher rates. How small the share is makes no difference.
A concrete example. Someone buying their first home purchases in London together with a sibling who owns a flat in Istanbul. Even if the sibling’s share is only 10 per cent, the additional dwelling rate is calculated on the whole purchase.
The same logic runs through the non-resident surcharge: if one of the buyers does not count as UK resident, the surcharge applies to the whole transaction.
The rates change from time to time; for the current figures and your own scenario use our stamp duty calculator. The band table and the detail of the surcharges are in our guide to buying a home in the UK.
There is one exception
A person with no beneficial interest at all in the other property does not count as a joint buyer. But that has to be documented in writing; a verbal statement is not enough.
What changes on the mortgage side?
- The lender assesses all applicants together: incomes are added up, but so are the liabilities, from credit card balances to maintenance payments.
- Everyone named on the title is normally named on the mortgage too. An owner who is on the title but not on the loan weakens the lender’s security and is not accepted.
- Liability for repayment is joint and several: if one co-owner does not pay, the lender can claim the whole amount from the other.
- One applicant’s credit history affects the other as well.
The terms are different again for buyers living abroad; we have gathered the options on our buy to let mortgage page.
What if one of you wants to sell?
This is the most commonly skipped part of a joint purchase, and the answer is written down before the purchase, not after. A declaration of trust, a statement of ownership, records the following: who contributed how much, who makes the monthly payments, whether the other has a right of first refusal if one wants out, how a decision to sell is taken, and how spending on renovation is reflected in the shares.
Without this deed a dispute goes to court, and the court looks at the structure on the title rather than at the money. If joint tenants was chosen, the shares are treated as equal even where one party paid 80 per cent.
Rental income and tax
Rental income is split according to the shares and each owner declares their own portion separately, using their own personal allowance and their own band. Owners living abroad each register separately under the non-resident landlord scheme. The detail is on our rental income tax page.
What to Check Before You Decide
- Work out the stamp duty together. If one of the co-buyers owns another home, your entire cost estimate changes.
- Choose the structure at the outset. The difference between joint tenants and tenants in common is costly to correct later.
- Have the declaration of trust drawn up alongside the purchase. It does not get done afterwards, once a dispute has started.
- Calculate your mortgage capacity jointly. Debts are added up just as incomes are.
- Talk through the exit. One of you may marry and move, the other may want to cash out; the answer to that belongs in the agreement.
Let us work out your joint purchase together: who comes in with what share, what the stamp duty will be, and how much you can borrow. Contact us